
A retailer can have money in the bank and no room left in the merchandise plan. It can also have buying room on paper while a deposit falls due before cash arrives. Open-to-buy planning helps control the first problem. It needs a separate cash check for the second.
For apparel, open to buy connects sales, markdowns, stock targets and orders due to arrive. It answers a precise question: how much more inventory can the buyer commit for a defined receipt period under the current plan?
This guide builds an original three-month apparel example, then follows the first month through receipts, new orders and a delivery delay. The figures are fictional. They teach a method; they are not targets for a particular retailer.
Define what is still open to buy
Planned receipts are all the goods the stock plan needs to receive. Available open to buy is the part of that requirement not already received or committed. Keep those two amounts distinct throughout the report.
Before a month starts, planned receipts less orders due that month gives the remaining buying room. During the month, subtract actual receipts as well as the still-outstanding orders. A received order must not stay in both categories.
Oracle's contextual OTB report makes this distinction explicit. It shows budget, received, outstanding and open amounts. The open amount is the budget less received and outstanding amounts.
Agree what creates a commitment in your process. A buyer's idea, an internal draft and an accepted purchase order do not mean the same thing. If draft proposals reserve budget, show those reservations separately from firm orders.
Choose one basis for each calculation
Retail-value OTB values goods at the selling-price basis used in the stock plan. Cost OTB uses merchandise cost. Unit OTB counts pieces. A calculation must not add retail sales dollars to inventory recorded at cost.
Shopify's OTB guide describes these three bases. Its explanation also shows why buying teams need consistent stock and order records. Use a clearly labelled basis even if the business maintains several linked views.
This article's main example uses USD at retail value, excluding sales tax. Sales are net sales on a matching basis. Markdowns are separate reductions in the retail stock ledger. There are no transfers, shrink losses or other adjustments in the first calculation.
These boundaries make the example easy to reconcile. A real plan must add the movements it actually has. Define them before entering values rather than adding a balancing number when the stock fails to tie.
Put the budget in the receipt period
The date an order is placed is not necessarily the period in which its goods support stock. A May order for August delivery belongs in August's receipt plan. Its deposit may belong in May's cash plan.
State whether your receipt point is the warehouse, store or another defined boundary. If the budget covers the whole owned network, moving a garment from its warehouse to a store is an internal transfer. It is not a second external purchase.
Use one calendar across sales, stock and orders. NRF's 4-5-4 calendar is a voluntary retail calendar designed to improve comparisons between periods. A business may use that calendar or calendar months, but should not mix their boundaries.
Keep the start and end dates in the file. “June” can mean different date ranges in two systems. A receipt near a period boundary can change apparent buying room even when the physical order is unchanged.
Derive the formula from the stock balance
Start with the inventory identity. Under the simplified retail-value assumptions, closing stock equals opening stock plus receipts, less net sales and markdown reductions.
Closing stock = opening stock + receipts − net sales − markdowns
Rearrange that identity to find the receipts needed to reach a target closing stock:
Planned receipts = target closing stock + planned sales + planned markdowns − opening stock
Each term is in the same currency and retail-value basis. Planned receipts are a flow during the period. Opening and closing stocks are values at two points in time. Mixing a current stock snapshot with a full month's unchanged flows breaks that time boundary.
The equation is a reconciliation tool. It does not forecast sales or decide the best closing stock. Those inputs need separate commercial judgement. A perfectly balanced plan can still contain an unrealistic sales forecast.
Understand why markdowns appear in a retail plan
Consider one garment entered into retail stock at USD 50. Its ticket price falls to USD 40. The retail stock ledger records a USD 10 reduction. When it sells at USD 40, a further USD 40 leaves through sales.
Together, markdown and sale remove the original USD 50 retail value. If sales are entered at the reduced price while the markdown is omitted, USD 10 appears to remain in stock even though the garment has gone.
That example assumes the markdown is recorded when the retail stock value changes. Your system may handle promotions and discounts differently. Map its definitions before using a standard formula. Do not record the same reduction in two input fields.
The merchandise's cost does not fall automatically by the ticket-price reduction. IAS 2's public summary addresses inventory cost and write-downs under that accounting standard. Accounting valuation has its own rules and evidence.
For a cost plan, use cost of goods sold and the cost-side movements defined by finance. Do not carry the retail markdown row across unchanged. This guide's retail stock identity is not a replacement for the accounting inventory schedule.
Build the first month's receipt requirement
The fictional tops department begins May with USD 100,000 of stock at retail. It plans USD 60,000 of net sales and USD 8,000 of markdown reductions. Its approved closing-stock target is USD 90,000.
Planned receipts are 90,000 + 60,000 + 8,000 − 100,000 = USD 58,000 at retail. This is the total receipt requirement before considering existing orders.
The buyer already has USD 22,000 of approved orders due in May. All remain unreceived at the opening date. Remaining OTB is therefore:
Opening May OTB = USD 58,000 − USD 22,000 = USD 36,000
Check the stock result if the plan is fully bought and delivered. Opening stock of 100,000 plus total receipts of 58,000, less sales of 60,000 and markdowns of 8,000, leaves 90,000. That matches the target.
The USD 36,000 is remaining retail-value buying room. It is not the cost of the next order and not a cash balance. It also does not identify which styles, colours or sizes the department should buy.
Make the outstanding-order figure trustworthy
Build on-order from line-level quantities that remain due. Remove received quantities. Reflect agreed cancellations and revised dates. Keep a link to the order and its latest confirmed delivery plan.
Oracle's buyer dashboard documentation distinguishes non-received approved quantities from received quantities. It also relates delivery changes to OTB periods. These definitions are useful even when a retailer uses another system.
A purchase-order status alone may not be enough. One order can be partly received, with the balance arriving later. Split the remaining quantities by the period in which they are expected to cross the chosen receipt boundary.
Do not remove a disputed or late order simply because it is inconvenient. Keep the commercial commitment visible until its status changes through the proper process. Show the delivery risk separately from the amount still committed.
Convert retail buying room to cost carefully
Suppose the new merchandise has an initial markup of 55% of its initial retail value. The cost complement is 100% − 55% = 45%. Under that specific assumption, USD 36,000 at retail corresponds to USD 16,200 at cost.
Indicative cost OTB = retail OTB × cost complement
Substitute 36,000 × 0.45 to obtain 16,200. This uses markup as a share of retail, not a markup added to cost. Keep that denominator in the definition.
For a single proposed garment with USD 60 initial retail and USD 27 cost, the complement is 27 ÷ 60 = 45%. Six hundred such garments would have USD 36,000 retail value and USD 16,200 merchandise cost.
That is an arithmetic illustration, not a recommendation to buy 600 units. The style demand, size mix, lead time and product limits still need review. OTB provides a budget boundary, not the assortment decision.
Use the actual purchase mix when margins differ
A department average may be a poor conversion for a specific order. Suppose USD 20,000 of retail buying room goes to goods with a 40% cost complement. Another USD 16,000 goes to goods with a 50% complement.
The two cost amounts are USD 8,000 and USD 8,000. Total cost is USD 16,000. Applying the earlier 45% average to all USD 36,000 would produce USD 16,200, which is USD 200 higher.
The difference comes from the mix. It is not a spreadsheet rounding error. Calculate the cost of known order lines directly. Use an average only for a clearly defined unallocated portion of the plan.
Keep freight, duty and other purchase costs on the agreed cost basis. Name what the conversion includes. A merchandise invoice value and a landed inventory cost may be different amounts, so both views should retain their labels.
Check cash on its own dates
Suppose the USD 16,200 order requires a 30% deposit at commitment and 70% later. The deposit is USD 4,860 and the balance is USD 11,340. Neither amount equals the USD 36,000 retail OTB.
Place those payments on their actual expected dates in the cash forecast. Include other committed payments and available funds. Positive OTB does not show that the deposit can be paid when due.
ApparelDiary's 13-week cash forecast guide explains dated cash movements in a factory context. The same separation of receipt planning from payment dates matters to a retailer. Keep the two plans linked through order identities.
The cash review may limit the order below the merchandise budget. If so, revise the buying decision openly. Do not alter the sales forecast just to make an unaffordable order appear permitted.
Update May without counting receipts twice
During May, the buyer commits another USD 8,000 at retail. Total approved receipts for May are now 22,000 + 8,000 = USD 30,000. The original USD 36,000 of free OTB has fallen to USD 28,000.
By the review date, USD 18,000 of those goods have arrived. The remaining approved on-order amount is USD 12,000. Total commitment still equals received plus outstanding: 18,000 + 12,000 = 30,000.
Actual sales to date are USD 24,000. Actual markdown reductions are USD 3,000. Under the simplified movement assumptions, current stock is 100,000 + 18,000 − 24,000 − 3,000 = USD 91,000.
The forecast still expects full-month sales of USD 60,000 and markdowns of USD 8,000. Remaining sales are therefore 36,000, and remaining markdowns are 5,000. The closing target stays at 90,000.
Remaining receipt need = 90,000 + 36,000 + 5,000 − 91,000 = USD 40,000
Subtract the USD 12,000 still on order. Remaining OTB is USD 28,000. This agrees with the full-month check: 58,000 planned receipts − 18,000 received − 12,000 outstanding.
Do not subtract the USD 18,000 again from the remaining-period formula. Its effect is already inside current stock. Choose either a full-period or remaining-period view, then keep its stock date and flows aligned.
Refresh actuals and forecasts on the same cut-off
Record the time through which sales, receipts, stock and order changes are included. A Monday stock snapshot paired with Wednesday receipts can invent additional stock. A received line left in an older on-order export can consume budget twice.
Oracle's in-season planning guidance discusses the need to capture receipts when planning updates occur between regular periods. The practical lesson is to reconcile the timing of each input.
Replace elapsed forecasts with actual results. Forecast the unelapsed part of the period. Do not retain both the original month's full forecast and actual sales as separate future stock deductions.
Keep the original approved plan for comparison. The working forecast may change every week, but the team still needs to know how much its view has moved and why.
Follow a late order into the next month
Suppose USD 10,000 of May's outstanding orders moves to June. May's remaining on-order amount falls from 12,000 to 2,000. With every other assumption unchanged, May OTB rises from 28,000 to 38,000.
June's on-order value rises by USD 10,000, reducing its free OTB by the same amount if its other inputs stay fixed. The delay has moved a commitment; it has not removed it from the season.
Before using May's apparent new room, ask what happens when both the replacement and the delayed goods arrive. A rush buy may solve a short-term gap while creating excess stock later.
Also revise the sales and stock assumptions if the delay changes product availability. Holding them constant helps explain the arithmetic. It does not mean the real business can still achieve the same sales.
Respond to negative OTB with a product decision
Return to the midmonth May position before the delay. Current stock is USD 91,000 and outstanding orders are USD 12,000. Now suppose the forecast for the rest of May falls to USD 6,000 of sales.
Keep remaining markdowns at USD 5,000 and closing stock at USD 90,000. Remaining receipt need becomes 90,000 + 6,000 + 5,000 − 91,000 = USD 10,000. The department already has 12,000 on order, so OTB is negative USD 2,000.
That result signals more committed receipts than the revised plan needs. It does not cancel a contract or create an automatic right to return goods. Review feasible date changes, agreed cancellations, transfers or a changed stock target.
Do not increase forecast sales merely to erase the negative number. Keep the demand evidence intact. Record the chosen response and its commercial consequences, then recalculate the plan.
Link the months into one season
The following opening plan uses the original May assumptions. Amounts are USD thousands at retail. Each month's closing stock becomes the next month's opening stock.
Plan line | May | June | July |
Opening stock | 100 | 90 | 95 |
Planned net sales | 60 | 75 | 65 |
Planned markdowns | 8 | 5 | 12 |
Target closing stock | 90 | 95 | 80 |
Total planned receipts | 58 | 85 | 62 |
On order at the opening review | 22 | 40 | 30 |
Available OTB | 36 | 45 | 32 |
June receipts are 95 + 75 + 5 − 90 = 85. July receipts are 80 + 65 + 12 − 95 = 62. After subtracting existing orders, their free OTB amounts are 45 and 32.
Across the three months, planned receipts total 205, sales total 200 and markdowns total 25. The season check is 100 + 205 − 200 − 25 = 80. Only the season's opening and closing stocks enter that check.
Do not add monthly opening stocks as if they were three separate purchases. The same stock flows across periods. That would count carried inventory more than once.
When actual May closing stock replaces its target, use that actual value to begin June's updated plan. Review later receipts rather than leaving the original chain disconnected.
Add other stock movements with the correct sign
The main example omits shrink and transfers. Add them explicitly when they exist. A confirmed stock loss reduces the balance, while a transfer into the planned location increases it. Each movement needs the same retail-value basis as the rest of this plan.
Suppose a store-level version of May's plan includes USD 2,000 of shrink and USD 6,000 of net transfers into the store. Begin with the original USD 58,000 receipt need. Add 2,000 for the loss and subtract 6,000 for the incoming transfer. External planned receipts become USD 54,000.
The closing-stock check is 100,000 + 54,000 + 6,000 − 60,000 − 8,000 − 2,000 = USD 90,000. With USD 22,000 of external receipts already on order, free OTB is USD 32,000. The transfer must have a credible source and date; an unapproved idea is not assured supply.
At total-network level, that internal transfer has a matching outward movement elsewhere. It cancels within the network boundary. Do not keep the store's positive transfer as a new company-wide source of goods.
Handle retail-value increases and other adjustments through their own defined fields. Ask finance and the stock-system owner how each event posts. Test one example through both the movement record and the closing balance before extending the spreadsheet to the full range.
Set closing stock from the next selling task
A closing-stock target should have a purpose. It may support the next launch, cover a replenishment gap or retain core sizes. The target should also reflect seasonal exit needs. Avoid holding a fixed amount simply because last year's spreadsheet did.
Check the physical mix behind the total. USD 90,000 of remaining stock could contain the wrong sizes or colours. A balanced financial plan does not guarantee that the intended shopper can find a suitable garment.
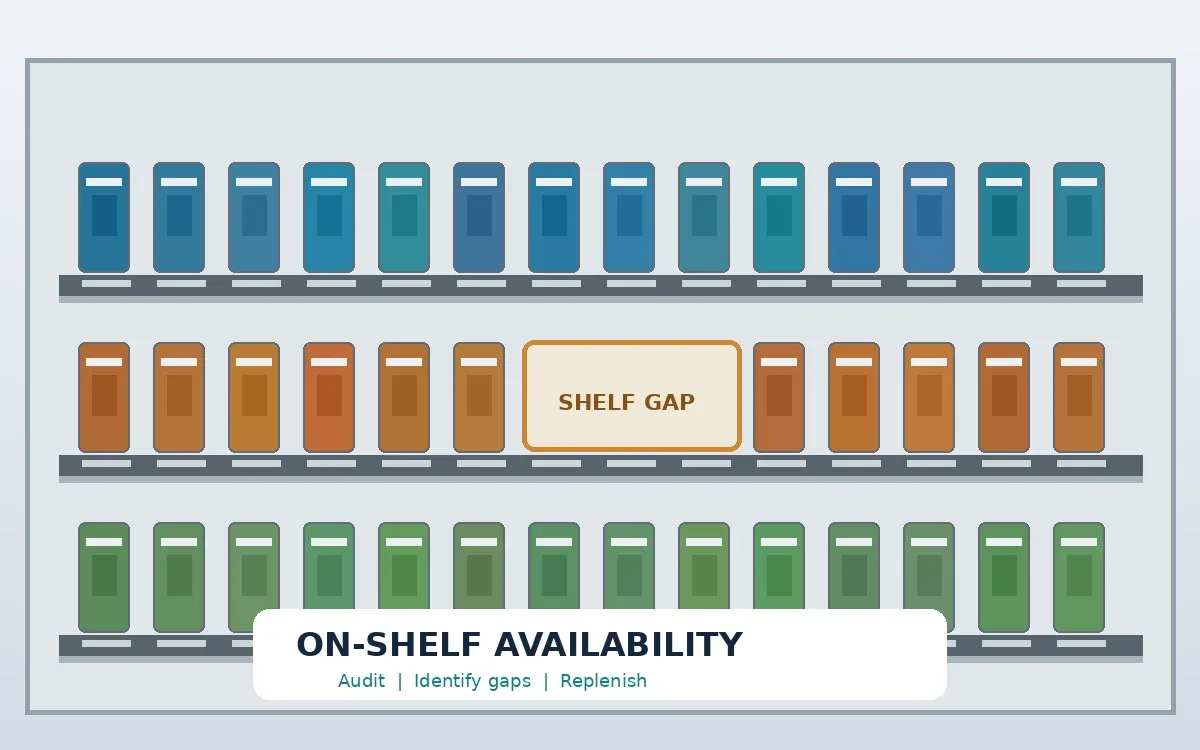
Use ApparelDiary's on-shelf availability guide to examine that separate execution problem. OTB controls future commitments. Variant availability checks whether the required product is present where the shopper needs it.
Challenge a large target change. Raising closing stock by USD 20,000 creates USD 20,000 more planned receipt need under unchanged assumptions. That is not new demand evidence. It is a decision to hold more stock and needs a reason.
Check stock states before importing a report
A system's “on hand” and “available” quantities may differ. Stock reserved for a customer or held for a quality check can remain physically present. Decide how the OTB inventory balance treats each state, then maintain a separate usable-stock view.
Shopify's inventory report documentation states that its reports changed from Available to On hand quantity on October 1, 2026. Earlier data retains its previous basis. That is a concrete reason to inspect definitions before comparing periods.
In the documented on-hand view, committed and unavailable units are included, while incoming transfer units are excluded. Do not treat a report total as free selling stock without reviewing its components.
Record the report version and extract date. If a definition changes, explain the break in the series. A sudden stock increase may come from a changed measure rather than a new buying decision.
Keep returns and transfers consistent with the boundary
Net sales may already include customer returns. A saleable returned garment may re-enter stock, while a damaged return needs a different status. Make sure the sales and inventory movements describe the same event without adding it twice.
Internal transfers also depend on the plan's scope. A receipt into one store is an issue from another location. At total-network level, the transfer itself does not create more owned merchandise.
Shopify's current purchase-order receiving guidance distinguishes the commercial order from its linked inventory transfer. It also notes that changes to one do not automatically update the other. Reconcile the actual movement with the commitment.
Review exceptions before releasing more buying room. Rejected units, supplier replacements and cancelled balances can leave different records. Resolve the expected supply and commercial status rather than inferring both from one screen label.
Run a review that produces a clear decision
Start with the stock and order reconciliation. Then review changes in sales, markdowns, closing targets and delivery dates. Show the resulting OTB movement by category and period so the buyer can trace its cause.
Oracle's merchandise financial planning overview separates pre-season plans from in-season review and approval. A smaller business can use the same distinction without adopting that software.
Give one person responsibility for the current approved budget. Record who can transfer room between categories or periods. A positive total should not silently cover an overcommitted category whose goods serve a different customer need.
Before approving an order, check its receipt period, retail and cost values, current commitments and cash dates. Preserve the version used for the decision. The next review should show what changed after approval.
Frequently asked questions
Is OTB the same as a purchase budget?
The total receipt budget includes goods already received or committed. Available OTB is the remaining uncommitted part. Use both labels so an opening budget is not mistaken for money still free to spend.
Does receiving a purchase order create new OTB?
Receiving normally moves value from outstanding to received. Their combined use of the receipt budget stays the same. A change in quantity, valuation, timing or plan may alter OTB, but receipt alone should not free the same commitment.
Can positive OTB justify any new style?
No. The proposed style still needs demand, timing, size and margin support. A department can have buying room while a specific style would add the wrong stock.
Should a negative amount be reset to zero?
Keep the negative value visible. It shows how far commitments exceed the plan. A separate rule may prevent new orders, but replacing the analytical amount with zero would hide the size of the issue.
Use OTB as a reconciled buying limit
An effective OTB plan connects the stock identity to actual commitments and receipt dates. It keeps retail and cost values distinct, updates the remaining forecast and carries stock correctly between periods. The result gives buyers a clear limit to work within, while demand, assortment and cash evidence determine which orders deserve that room.
An open-to-buy plan depends on demand estimates, so see exponential smoothing for demand planning, forecast accuracy with MAE and WAPE, on-shelf availability and the Zara business model.
References
Oracle: Contextual OTB budget, received, outstanding and open measures.
Shopify: Open-to-buy planning and valuation bases.
NRF: The voluntary 4-5-4 retail calendar.
IFRS Foundation: IAS 2 inventory cost and valuation, public summary.
Oracle: Buyer dashboard, outstanding orders and shipment timing.
Oracle: In-season targets, receipts and open-to-buy adjustments.
Shopify Help: Inventory report definitions and the October 2026 change.
Shopify Help: Purchase orders and linked inventory receiving.
Oracle: Merchandise financial planning, original plans and in-season review.
Discussion0
Loading the discussion…