
A seasonal range can look profitable at its ticket price and still leave the business with a costly exit. The useful question changes as the season ends. The team must decide how to recover value from the stock it actually holds, within the selling time and routes that remain.
Seasonal apparel markdown planning connects a price path to a dated stock exit. It needs more than a discount percentage. It needs available units, expected sales at each price, selling costs and a credible destination for the remainder.
This guide follows a fictional six-week clearance of six hundred garments. It compares three possible plans, tests a weaker residual price and shows how to update the required sales pace. Every price, cost and sales volume in the example is an assumption. None is an industry benchmark or a guaranteed demand response.
Set the exit decision before choosing a discount
Write down what must be true at the end of the plan. A shop may need the fixture clear for its next range. A warehouse may have a final collection date for a bulk buyer. A brand may allow a limited carryover into the next season. These are different exit conditions.
Separate the final retail selling date from the physical removal date and the payment date. A sale order on Friday does not release a rack if the garments remain there until Monday. Nor does it produce cash immediately if the buyer pays later.
Define the stock boundary too. Include the relevant styles, colours, sizes, stores and online inventory. Distinguish sellable stock from damaged, reserved or disputed units. A clearance forecast built on total system stock can promise sales from garments that customers cannot buy.
Oracle's clearance documentation treats clearance markdowns as permanent price changes within that system. It also supports a later reset to regular price. Other teams use markdown more broadly. Agree on the term and event type so a seasonal exit does not get confused with a short promotion.
The decision record should name the person who approves the price, the person who confirms stock and the person who owns the terminal route. If those roles disagree about the deadline or quantity, resolve that gap before approving the first price change.
Build the stock and price record
Start with a dated count or reconciled stock position. Show opening units, expected receipts, returns, transfers and known losses. Keep each movement separate. A transfer between two stores changes location stock but does not remove inventory from the business.
Inspect the size mix as well as the total. A hundred garments spread across useful sizes may sell differently from a hundred units in one residual size. A style-level forecast should not assume that the original size curve is still available at the end of the season.
Keep regular price, current price and proposed price in distinct fields. Record the effective dates and channels. A previous temporary offer may affect both customer expectations and the evidence allowed for a public saving claim. It should not disappear when the spreadsheet is refreshed.
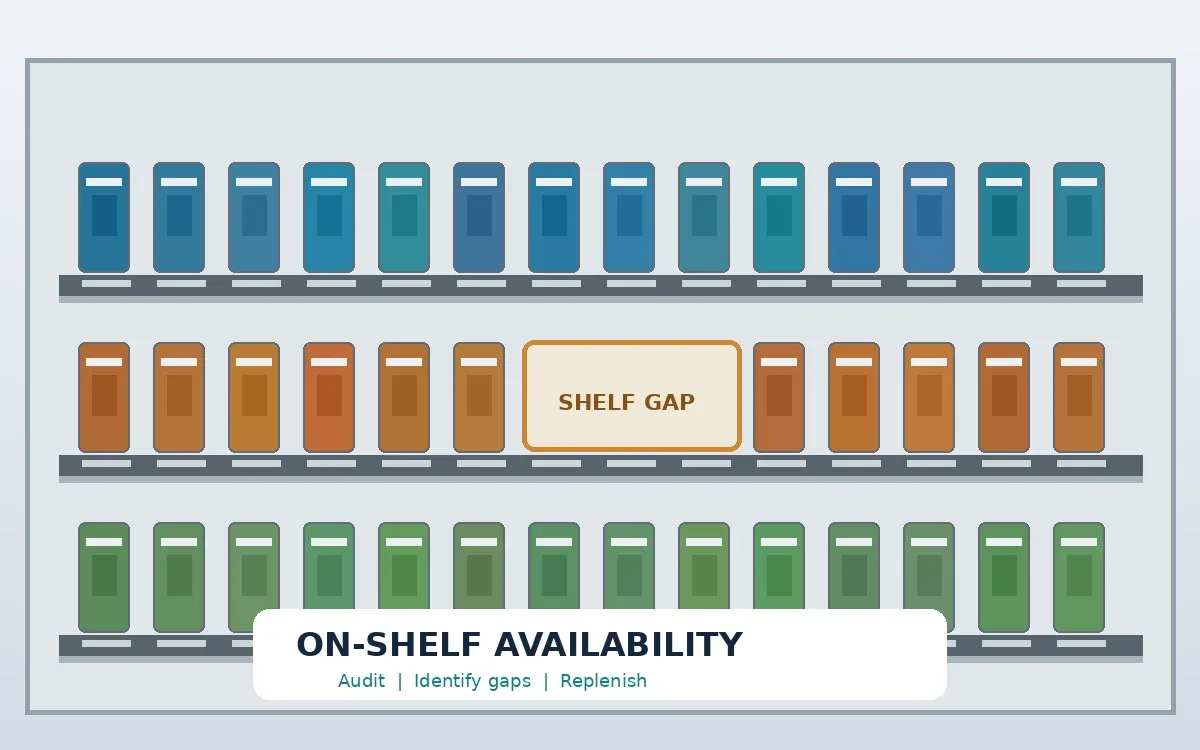
Check whether weak sales reflect the price or a selling obstacle. The item may be missing from the fixture, hard to find online or wrongly marked unavailable. ApparelDiary's retail availability audit helps investigate that problem. Cutting the price cannot fix a garment that shoppers cannot locate.
Then record the costs that will change with the chosen route. Examples include picking, packing, payment charges, transfer freight and bulk handling. State whether each cost is per unit, per order, per shipment or fixed for the event. Mixed cost bases are a common source of false savings.
Make sales assumptions visible
A candidate price needs an expected sales path, not just a total. State what the team expects to sell in each remaining week and location. Cap sales at available stock. Flag any plan that assumes a popular size remains available after it has already sold out.
Use comparable evidence where possible. Check the season stage, product type, original price, weather, channel and remaining sizes. A past promotion on a fully stocked range may be a poor guide to a broken assortment near its exit date.
Caro and Gallien's clearance-pricing research, published in 2012, combined demand forecasting with pricing decisions in a fast-fashion setting. Its value here is the link between the forecast and the decision. The historical study does not supply a universal discount schedule for another retailer today.
Likewise, Shopify's Smart Pricing documentation describes price advice based on stock, sales, seasonality and cost. That is a description of the service's inputs. A suggestion still needs review against the retailer's own deadline, restrictions and evidence.
Mark an estimate as a scenario when its response has not been validated. Avoid calling a lower-price sales total a forecast merely because it appears in a formula. The most detailed workbook can still depend on a weak assumption about what shoppers will buy.
Calculate discount depth on the right base
The example garments have a regular price of USD 50. A first markdown to USD 40 reduces the price by USD 10. Divide ten by the original fifty to get 0.20, or a 20% reduction.
Let P0 be the original price and P1 the new price, both in dollars. Let d be the discount as a decimal fraction.
d = (P0 − P1) ÷ P0
If the price later falls from USD 40 to USD 30, the further reduction is 10 ÷ 40 = 25%. The final USD 30 price is 20 ÷ 50 = 40% below the original USD 50 price.
Do not add 20% and 25% and call the total reduction 45%. The second percentage uses a different base. The retained price shares multiply: 0.80 × 0.75 = 0.60. The final price is therefore 60% of the original, which means a 40% total reduction.
Label both percentages when planning a sequence. One field can show the step from the current price. Another can show the total change from the original price. This makes the next instruction easier to execute and the advertised saving easier to review.
Compare three six-week exit plans
Assume the retailer owns six hundred sellable garments at a historical merchandise cost of USD 20 each. The total cost is USD 12,000. All example selling prices exclude tax. There are no new receipts, returns, transfers or losses in this base case.
Each retail sale incurs USD 2 of additional handling cost. At the deadline, an approved bulk buyer takes all residual units for USD 10 each. Bulk handling costs USD 1 per unit. Assume the buyer can accept up to three hundred units and pays within the review period.
These conditions are deliberate simplifications. A real bulk offer needs a confirmed quantity, condition, destination, collection date and payment basis. An unconfirmed resale estimate is not equivalent to an agreed exit route.
Plan | Retail price path | Assumed retail sales | Residual units | Net recovery |
A | USD 40 for all six weeks | 300 at USD 40 | 300 | USD 14,100 |
B | USD 30 from the start | 480 at USD 30 | 120 | USD 14,520 |
C | USD 40 for two weeks, then USD 30 | 80 at USD 40 and 360 at USD 30 | 160 | USD 14,560 |
Here, net recovery means sales proceeds from both routes less the stated future handling costs. It excludes the historical stock cost. It also excludes fixed overhead, tax and any other costs not stated in the example. It is not net profit.
Let R be retail sales proceeds, B bulk proceeds and V the additional selling and handling costs. All three are measured in dollars over the same exit horizon.
Net recovery = R + B − V
Work through Plan A
Retail proceeds are 300 × USD 40 = USD 12,000. The three hundred residual units generate 300 × USD 10 = USD 3,000. Total proceeds are USD 15,000.
Retail handling is 300 × USD 2 = USD 600. Bulk handling is 300 × USD 1 = USD 300. Subtract the combined USD 900 from USD 15,000 to obtain USD 14,100 of net recovery.
The unit reconciliation is three hundred retail sales plus three hundred bulk sales, equal to six hundred opening units. No stock remains after the bulk collection. Half the stock leaves through the regular retail channel and half through the terminal route.
Work through Plan B
Retail proceeds are 480 × USD 30 = USD 14,400. The remaining one hundred and twenty units generate USD 1,200. Total proceeds reach USD 15,600.
Retail handling is USD 960 and bulk handling is USD 120. The combined USD 1,080 cost leaves net recovery of USD 14,520. This is USD 420 more than Plan A under the stated sales assumptions.
Plan B sells more units to shoppers at a lower price. The lower unit price does not by itself establish a worse outcome. The comparison must include the units that would otherwise leave through the lower-value bulk route.
Work through Plan C
The first eighty retail sales produce 80 × USD 40 = USD 3,200. The next three hundred and sixty produce 360 × USD 30 = USD 10,800. Retail proceeds total USD 14,000.
The one hundred and sixty residual units add USD 1,600. Retail handling is 440 × USD 2 = USD 880. Bulk handling is USD 160. Net recovery is therefore 15,600 − 880 − 160 = USD 14,560.
Plan C exceeds Plan B by only USD 40. That small difference should make the team examine the assumptions closely. A minor change in sales, labour or the terminal offer could reverse the ranking. The table compares three candidates; it does not prove that one is globally optimal.
Separate the forward decision from the full merchandise result
The USD 12,000 stock cost has already been incurred in this example. It is the same for all three routes. Subtracting it from each net recovery leaves USD 2,100 for A, USD 2,520 for B and USD 2,560 for C.
Those figures are simplified merchandise results after the stated handling costs. They still do not include all business expenses. The subtraction changes the reported amount but not the ranking, because the same historical cost applies to every candidate.
Do not count that cost twice. A workbook that subtracts cost of goods from each sale and then deducts the original purchase again will understate the result. Conversely, a positive cash recovery should not be presented as proof that the original buy earned a profit.
Some costs are still avoidable even late in the season. A supplier order may not yet be committed, or a separate storage contract may be cancellable. Those amounts belong in the decision if the available actions change them. The relevant boundary must come from the actual agreements.
Book value needs its own review. Under IAS 2's public guidance, inventory valuation considers cost and the amount expected from sale after relevant completion and selling costs. A price change does not let a planner replace that accounting assessment with an arbitrary discount percentage. Finance should review the stock and the evidence using the applicable policy.
Stress-test the residual route
Now assume the bulk selling price falls from USD 10 to USD 6. Keep all retail volumes, retail prices and handling costs unchanged. This is a separate scenario, not a claim about the probability of a resale-price fall.
Plan A's bulk proceeds fall to 300 × USD 6 = USD 1,800. Net recovery becomes 12,000 + 1,800 − 900 = USD 12,900. The drop from its base case is USD 1,200.
Plan B's bulk proceeds become USD 720. Net recovery is 14,400 + 720 − 1,080 = USD 14,040. Plan C's bulk proceeds become USD 960, leaving 14,000 + 960 − 1,040 = USD 13,920.
Plan B now exceeds Plan C by USD 120. The earlier choice has reversed. B depends on fewer terminal units, so the weaker bulk price harms it less. This is why the residual route deserves a clear assumption and its own sensitivity check.
Find the residual price that changes the choice
The two closer candidates can be compared without rebuilding every row. Let s be the bulk selling price in dollars per unit. Keep the assumed retail sales and all handling costs fixed. Plan B has USD 14,400 of retail proceeds and USD 1,080 of total handling costs. Its net recovery is 13,320 + 120s.
Plan C has USD 14,000 of retail proceeds and USD 1,040 of total handling costs. Its net recovery is 12,960 + 160s. Subtract B from C to obtain a difference of 40s minus USD 360.
Recovery difference, C less B = 40s − 360
Set the difference to zero. Divide USD 360 by forty units to find a bulk-price switching point of USD 9 per unit. At that price, each plan returns USD 14,400 after the stated handling costs. Above nine dollars, C is higher. Below nine dollars, B is higher, under these fixed assumptions.
This threshold helps direct the next piece of research. If a confirmed bulk offer is comfortably below USD 9, the base-case preference for C has weak support. If the offer is uncertain around nine dollars, small changes in retail sales or handling costs deserve closer review.
The threshold is conditional. It is not a forecast, a recommended selling price or a confidence interval. A bulk buyer may offer different prices for different quantities or size mixes. In that case, one common value of s would not describe both plans fairly.
Also avoid changing several uncertain inputs in only the favoured plan. Use the same scenario logic across candidates. A weaker season may lower both retail sales and bulk demand. A review that lowers only one of those inputs can understate the risk. Show a combined adverse case when the commercial evidence supports that relationship.
Capacity can matter more than price. If the buyer can take only one hundred units, all three base plans leave some stock without an approved route. Do not hide that problem by assigning the excess a fictional cash value. Add a feasible route or revise the retail plan.
Also check timing. A higher bulk price paid months later may not solve an immediate cash need. Add the actual expected payment dates to the cash view. Keep those timing effects separate from the undiscounted six-week arithmetic shown here.
Translate the exit target into a weekly pace
Suppose the team chooses a retail-sales target of four hundred and eighty units. That leaves at most one hundred and twenty units for bulk exit. With six hundred opening units and six weeks, the required average retail pace is eighty units per week.
Let Q be sellable units available for the remaining period, E the allowed residual units and W the selling weeks left. The simple pace calculation assumes no other stock movements.
Required weekly sales = (Q − E) ÷ W
At the start, substitute Q = 600, E = 120 and W = 6. The result is (600 − 120) ÷ 6 = 80. An average pace is a planning check. It does not imply that demand will be even across weeks.
After two weeks, suppose actual sales are only one hundred and ten units. Remaining stock is four hundred and ninety. Four weeks remain. To reach the same residual target, the business must sell (490 − 120) ÷ 4 = 92.5 units per week on average.
Garments remain whole units. A feasible weekly quantity pattern could be ninety-three, ninety-three, ninety-two and ninety-two, totalling three hundred and seventy. The half unit describes an average, not a picking instruction.
Use this calculation to trigger a decision, not to dictate a discount. Check why sales missed the path. Review availability, execution and the demand assumption. Then compare the next price, a transfer or a revised terminal route. A steeper reduction is one possible action, not the automatic answer.
If receipts or returns will add sellable stock, include them explicitly. If the remaining weeks contain fewer trading days, use a suitable daily calendar. The denominator must reflect the time customers can actually buy the garments.
Keep location and assortment constraints in the plan
Stock concentration can make an attractive chain-wide plan impossible. One store may hold most of a slow size while another has demand but little stock. A proposed transfer needs enough time to pick, move, receive and display the garments before the selling window closes.
An MIT study on clearance distribution and pricing examined those decisions together in a historical fast-fashion case. Its general lesson supports a practical question: can the planned stock be present where the assumed sales occur? The study's numerical findings should not be copied as expected gains elsewhere.
Price coordination also has limits. A common reduction across a style can simplify execution, but some colours or locations may have very different stock risks. A local price may preserve value, yet require more control over signs, transfers and customer queries.
Oracle's markdown-rule documentation includes exit dates, sell-through targets, salvage assumptions and restrictions on markdown count or timing. These are configurable planning rules. They are not universal industry limits or proof that any chosen rule is commercially sound.
List the real restrictions before comparing candidates. Include price authority, location scope, lead time, terminal capacity and any supplier or brand conditions. Reject an infeasible plan before ranking its apparent financial benefit.
Execute the approved prices and claims
The release record should identify the item or variant, location, old price, new price, effective time and approving owner. Include the next review date. Confirm that the store or online channel received the instruction and applied it at the intended time.
For Google product listings, the sale-price effective-date guidance recommends explicit dates, times and time zones. This matters when a website and advertising feed change on different schedules. Test the customer-visible price through checkout after the event starts.
Review price claims separately from internal planning percentages. In the United States, 16 CFR 233.1 addresses genuine former prices and misleading comparisons. Raising a reference price simply to advertise a larger reduction conflicts with that guidance. Other destinations have their own requirements.
Keep evidence of the relevant price history and the actual offer terms. Do not imply that every variant is reduced by the largest advertised percentage. State any conditions clearly and review the planned wording for the market where it will appear.
Review what happened and improve the next buy
Close the event with a stock balance and a money balance. Reconcile retail units, bulk units, returns, losses and residual stock. Match actual proceeds and extra costs to the agreed routes. Investigate any gap instead of treating a low closing balance as proof of a successful clearance.
Compare the assumed and actual sales path. Preserve the version used for approval. Separate a weak forecast from a price that was applied late or a transfer that never reached the shop. These causes lead to different improvements next season.
Do not call the entire clearance volume incremental demand. Some shoppers would have bought at a higher price. ApparelDiary's trade-promotion effectiveness guide explains the separate task of estimating lift against a credible baseline. This exit workbook answers which feasible route recovers value from the remaining stock.
Use the review to change the next buy where evidence supports it. The issue may be too many options, too much depth, a poor size mix or a late delivery. A well-run clearance can limit damage while still revealing a buying decision that needs correction.
Frequently asked questions
Should every seasonal item follow the same markdown dates?
No. Products can have different selling windows, stock risks and restrictions. A shared calendar helps coordination, but each item's plan still needs a credible sales path and terminal route. Explain exceptions rather than forcing unlike items into the same schedule.
Is the plan with the highest sell-through always best?
No. More retail units can come at a large price sacrifice or selling cost. Compare net recovery, remaining stock and feasibility together. In the worked case, the best base result and the largest retail volume belong to different plans.
Can stock be sold below its original cost?
An exit decision may involve that option, subject to the actual commercial and market rules. Compare its future proceeds and costs with feasible alternatives. Keep the full merchandise loss visible and obtain the required approval. A past cost should neither be hidden nor charged twice.
What if there is no reliable demand estimate?
Use explicit scenarios and show where the choice changes. Review actual results at short, useful intervals. Gather evidence on comparable items and correct selling obstacles. Avoid a false claim of precision or an automatic discount rule unsupported by the available data.
Make the exit measurable
A useful seasonal markdown plan ends with a clear stock destination. Start with verified quantities and a real deadline. Compare price paths on the same cost and time basis, test the residual route and monitor the remaining sales pace. Then reconcile the outcome so the next buying and pricing decisions benefit from what the season actually taught.
Markdown plans rely on demand and stock data, so see on-shelf availability, forecast accuracy and exponential smoothing.
References
Oracle: Clearance event definitions, approvals and execution.
Shopify: Smart Pricing markdown and markup inputs.
IFRS Foundation: IAS 2 inventory cost and valuation guidance.
MIT: Coordination of inventory distribution and price markdowns, 2010 thesis abstract.
Oracle: Promotion and markdown pricing rules.
Google Merchant Center: Sale-price effective dates and time zones.
Discussion0
Loading the discussion…